Inflation, oil and AI: the forces shaping markets
Share
Markets are currently dealing with heightened levels of volatility, driven by an unusual number of moving parts at once.
In most years a small number of events typically set the tone, but at the moment several factors are pulling markets in different directions. Globally, bond yields are moving higher, the oil price is trading around US$100 a barrel and central banks have begun raising rates again after a short-lived period of monetary easing. Set against those pressures is an enormous wave of company spending on artificial intelligence, which continues to support profits and has so far offset much of the strain elsewhere.
Where markets stand
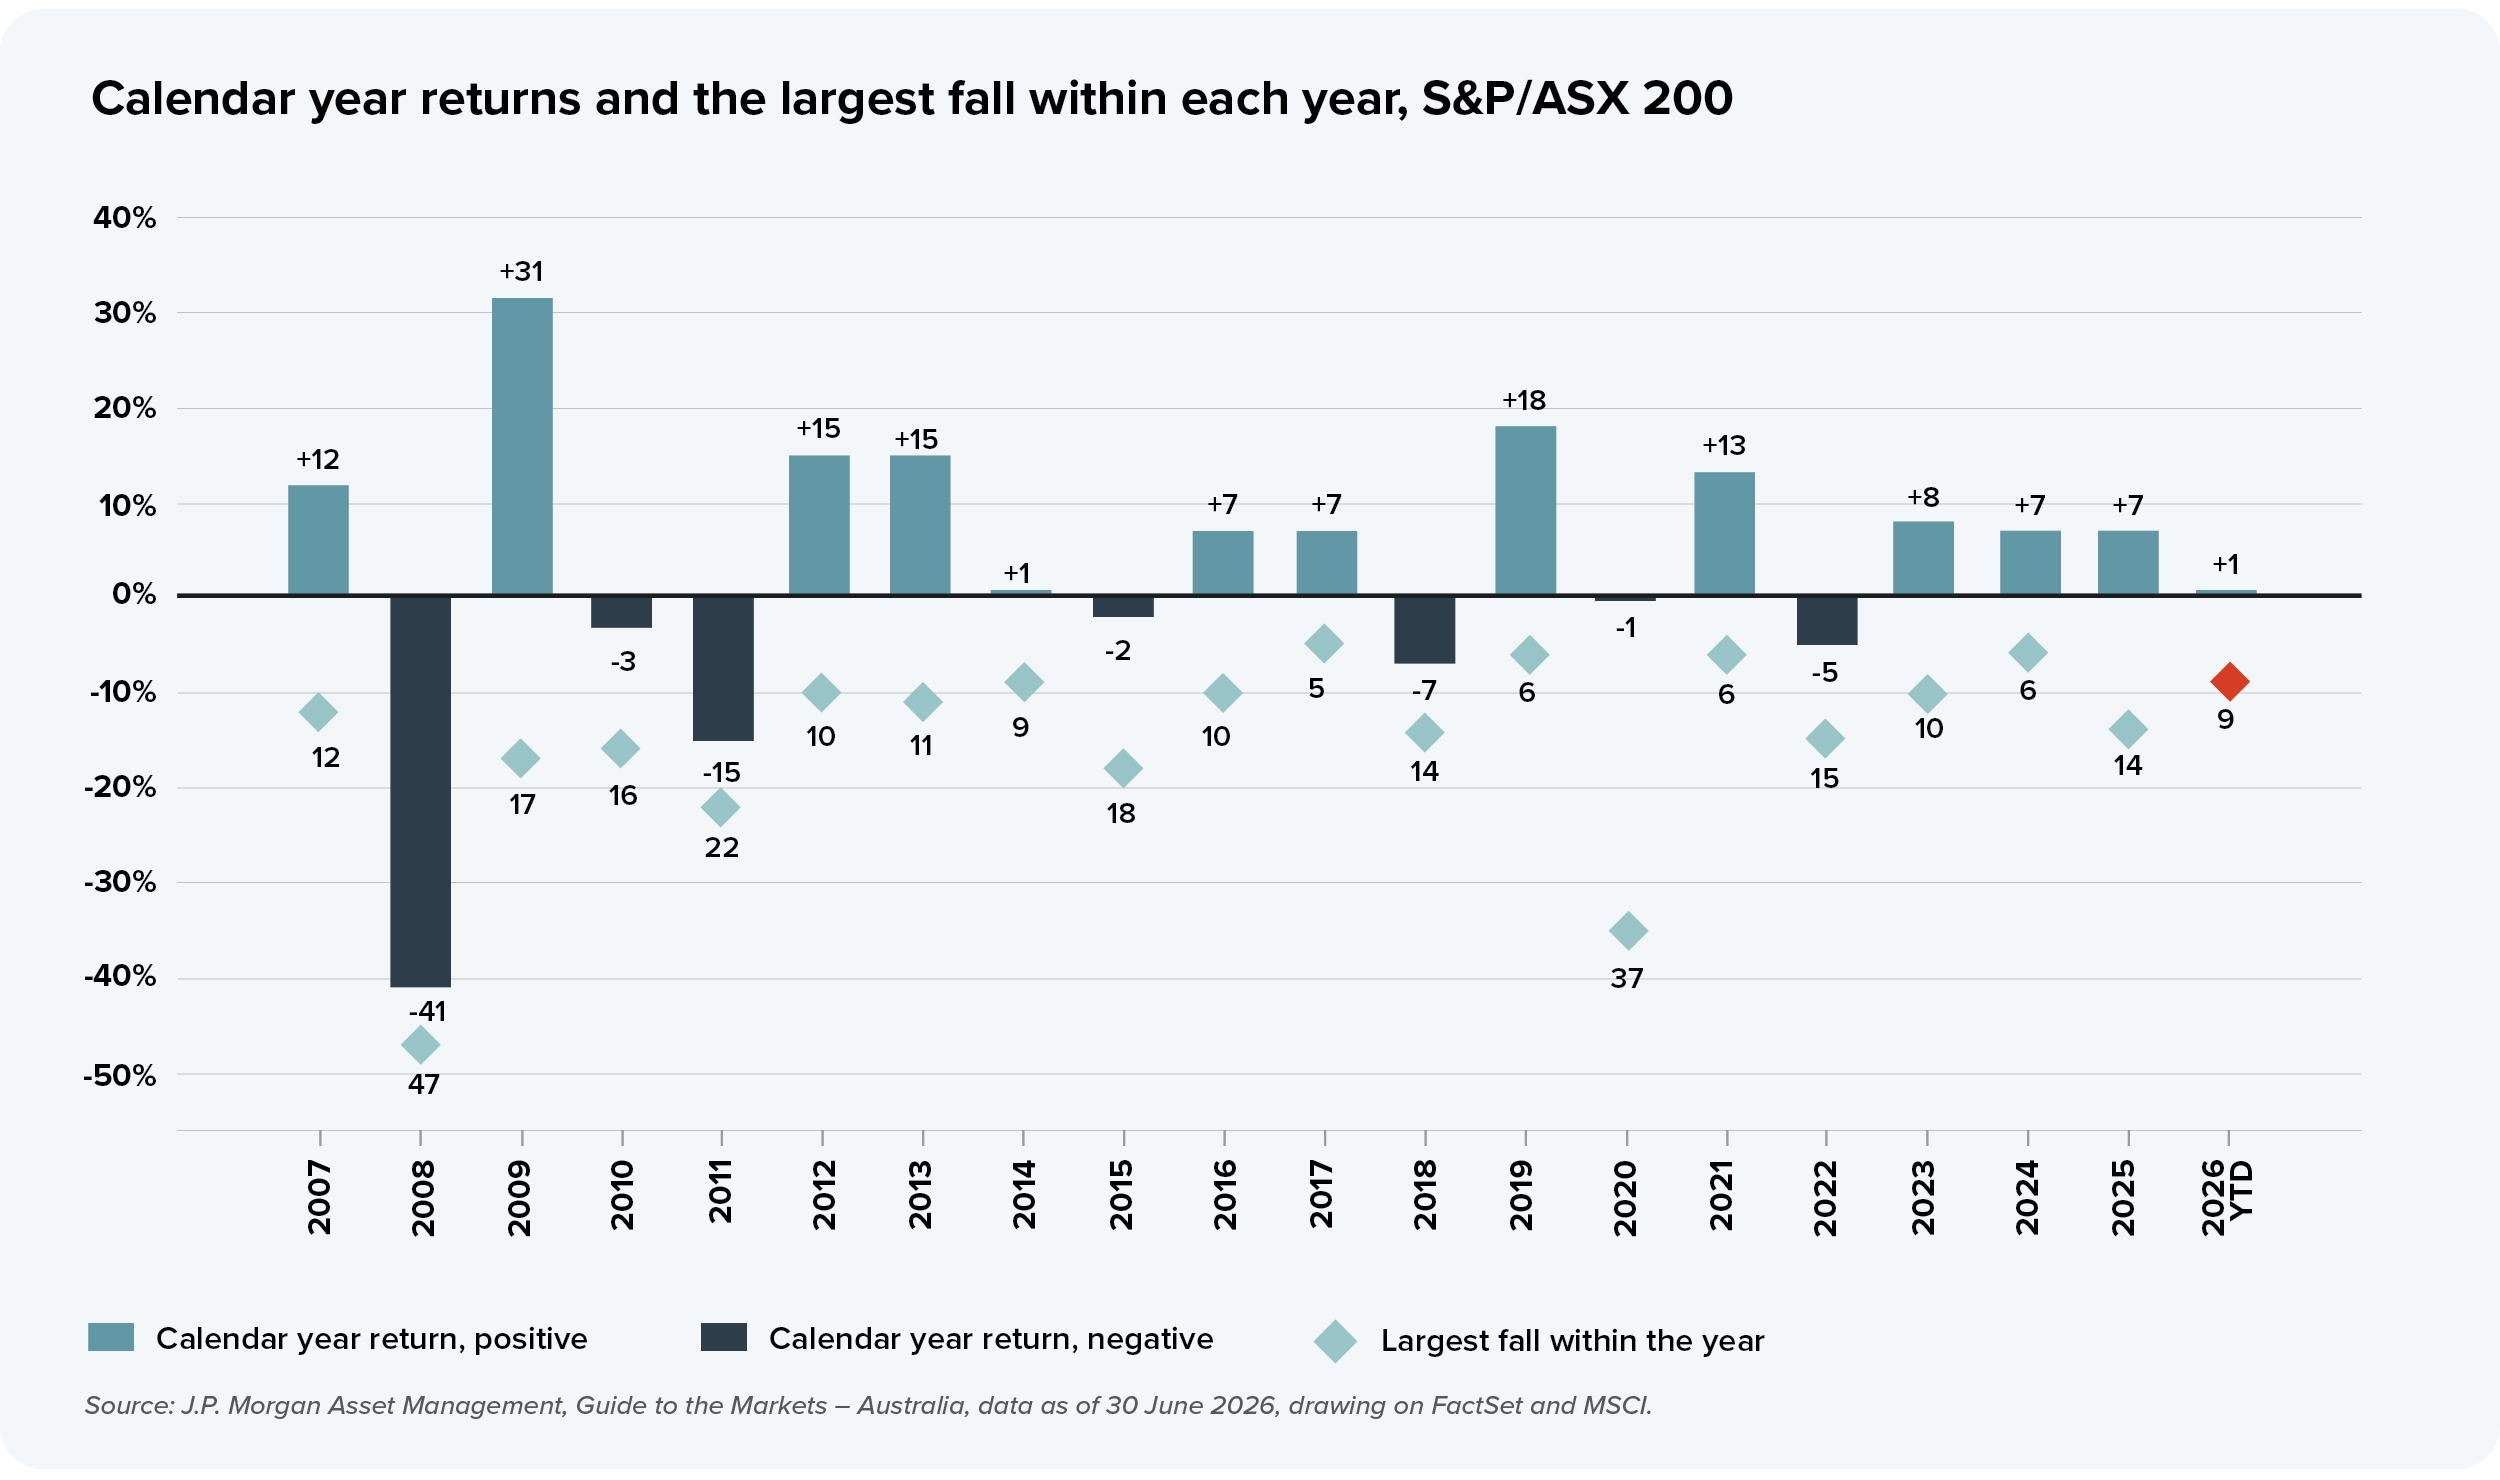
The Australian share market currently sits about 7% below the record high it set in early August, with US markets also drifting lower. As shown below, a fall of this size is not irregular and most years tend to bring drops of this magnitude.
Why bond yields are rising
The yield on 10-year U.S. Treasuries is at its highest level in almost two decades, while in Australia, the 10-year Government Bond has reached levels not seen since 2011. Several factors are driving this spike in bond yields:
the US-Iran conflict escalation has pushed oil prices sharply higher, reviving inflation fears;
governments are borrowing heavily to cover their deficits and their spending; and
a number of central banks have raised rates.
For the first time since 2023 the Federal Reserve has increased the cash rate by 25 bps and the Reserve Bank of Australia (RBA) also lifted the cash rate a further 25 bps to 4.60% on 29 September. In the corporate sector, heavy debt issuance by the very largest technology companies to fund AI infrastructure has increased the supply of corporate bonds, putting further upward pressure on broader bond yields.
Why the oil price is rising
Brent crude traded as high as US$105 a barrel in mid-September, but has since settled to $100 a barrel in recent weeks. Attacks on shipping routes and oil facilities in the Middle East have disrupted a supply chain already under strain. Rising oil costs for households and businesses will feed straight into inflation, applying further pressure on central banks to keep interest rates higher for longer.
A further, more recent risk is a potential US ban on diesel exports, which President Trump has signalled support for as a way to ease domestic fuel prices ahead of the November midterm elections. Australia is the world's largest importer of diesel in absolute terms and given the economy's reliance on diesel for mining, agriculture and freight, this is a risk we are watching closely as a potential further source of inflationary pressure.
Private credit
Closer to home, Sydney developer Bathla Group was placed in administration in late August owing about A$3.3 billion, almost all of it to private credit funds rather than to banks. Private credit is lending done by investment funds and other non-bank lenders. Around 40 funds are exposed and several have limited or suspended investor withdrawals. The chair of ASIC called it the first significant crack in a sector that now exceeds A$200 billion. More recently, Metrics Credit Partners, one of Australia’s largest private lenders has been forced to devalue assets across three ASX-listed funds by a total of $168 million.
Our model portfolios currently hold only a small exposure to private credit and no exposure to Bathla or Metrics. We partner with specialist fund managers such as Kapstream and Realm, who provide funding to non-bank lenders. These lenders make loans across a broad range of borrowers, including home, car and personal loans. This structure spreads exposure across thousands of individual loans, reducing reliance on any single borrower.
The Australian private credit market remains relatively small on a global scale and is highly concentrated in the property sector, which makes it susceptible to a single credit cycle. Overseas, US and European direct lending markets give access to diversified corporate borrowers, established managers and stronger structural protections. We continue to monitor developments closely in this sector.
What is holding markets up
Against all of that sits one very large positive: companies are spending an enormous amount of money building the infrastructure required to support the growth in artificial intelligence (AI). The four largest US technology companies (Amazon, Alphabet, Meta and Microsoft) expect to spend roughly US$725 billion this year on AI, most of it directed at AI data centres, Nvidia GPUs, custom silicon and power, with estimates suggesting that this figure will be closer to US$1 trillion in 2027.
That spending flows well beyond the technology sector. It supports the companies that make semiconductors, the firms that build and cool data centres and the utilities and infrastructure businesses that supply them with power. It is one of the main reasons company earnings have held up this year while interest rates, oil and trade policy have all moved the wrong way.
What this means for your portfolio
Findex models have been constructed with a range of outcomes in mind, which makes them well positioned to cope with sharp market moves. In practice, that means holding a diversified portfolio of assets that behave differently when an event unfolds.
We recently increased the weighting to real assets such as infrastructure within our model portfolios. Airports, pipelines and utilities often earn income that is linked to inflation, so their revenue rises when prices do. We also added exposure to technology-enabled companies that are either developing the infrastructure, data and software that power AI, or using AI to improve products, productivity and customer experiences. Our models also continue to hold exposure to floating rate securities, which reset their interest payments upwards as interest rates rise.
No portfolio can avoid every downturn and we will not pretend otherwise. Diversification reduces the chance that any single event decides your outcome. Periods like this can be uncomfortable, but they are also normal. Your portfolio is built to absorb them.
General advice warning. This document contains general information only. It has been prepared without taking into account your objectives, financial situation or needs. Before acting on any information in this document, you should consider its appropriateness having regard to your own objectives, financial situation and needs, and seek advice from a qualified adviser. Past performance is not a reliable indicator of future performance. Market data is sourced from third party providers and is current as at the close on 15 September 2026.
Findex Advice Services Pty Ltd, ABN 88 090 684 521, AFSL 243253
For more than twenty years, Matthew has held a variety of client advisory and corporate roles across the Wealth Management industry in Australia and the UK, with a particular focus on high-net-worth individuals and families, as well as not-for-profit organisations. As Head of Investment Relations for Findex, Matthew works in collaboration with the Findex Investment Team and Findex Financial Advisers to help construct and deliver the Findex investment proposition to clients.
Matthew holds a Bachelor of Commerce and a Graduate Diploma in Applied Finance. He is a member of the Financial Planning Association of Australia (FPA) and the Financial Services Institute of Australasia (FINSIA).